Insurance Partnerships: Building a Second Revenue Line in a Motorcycle Dealership
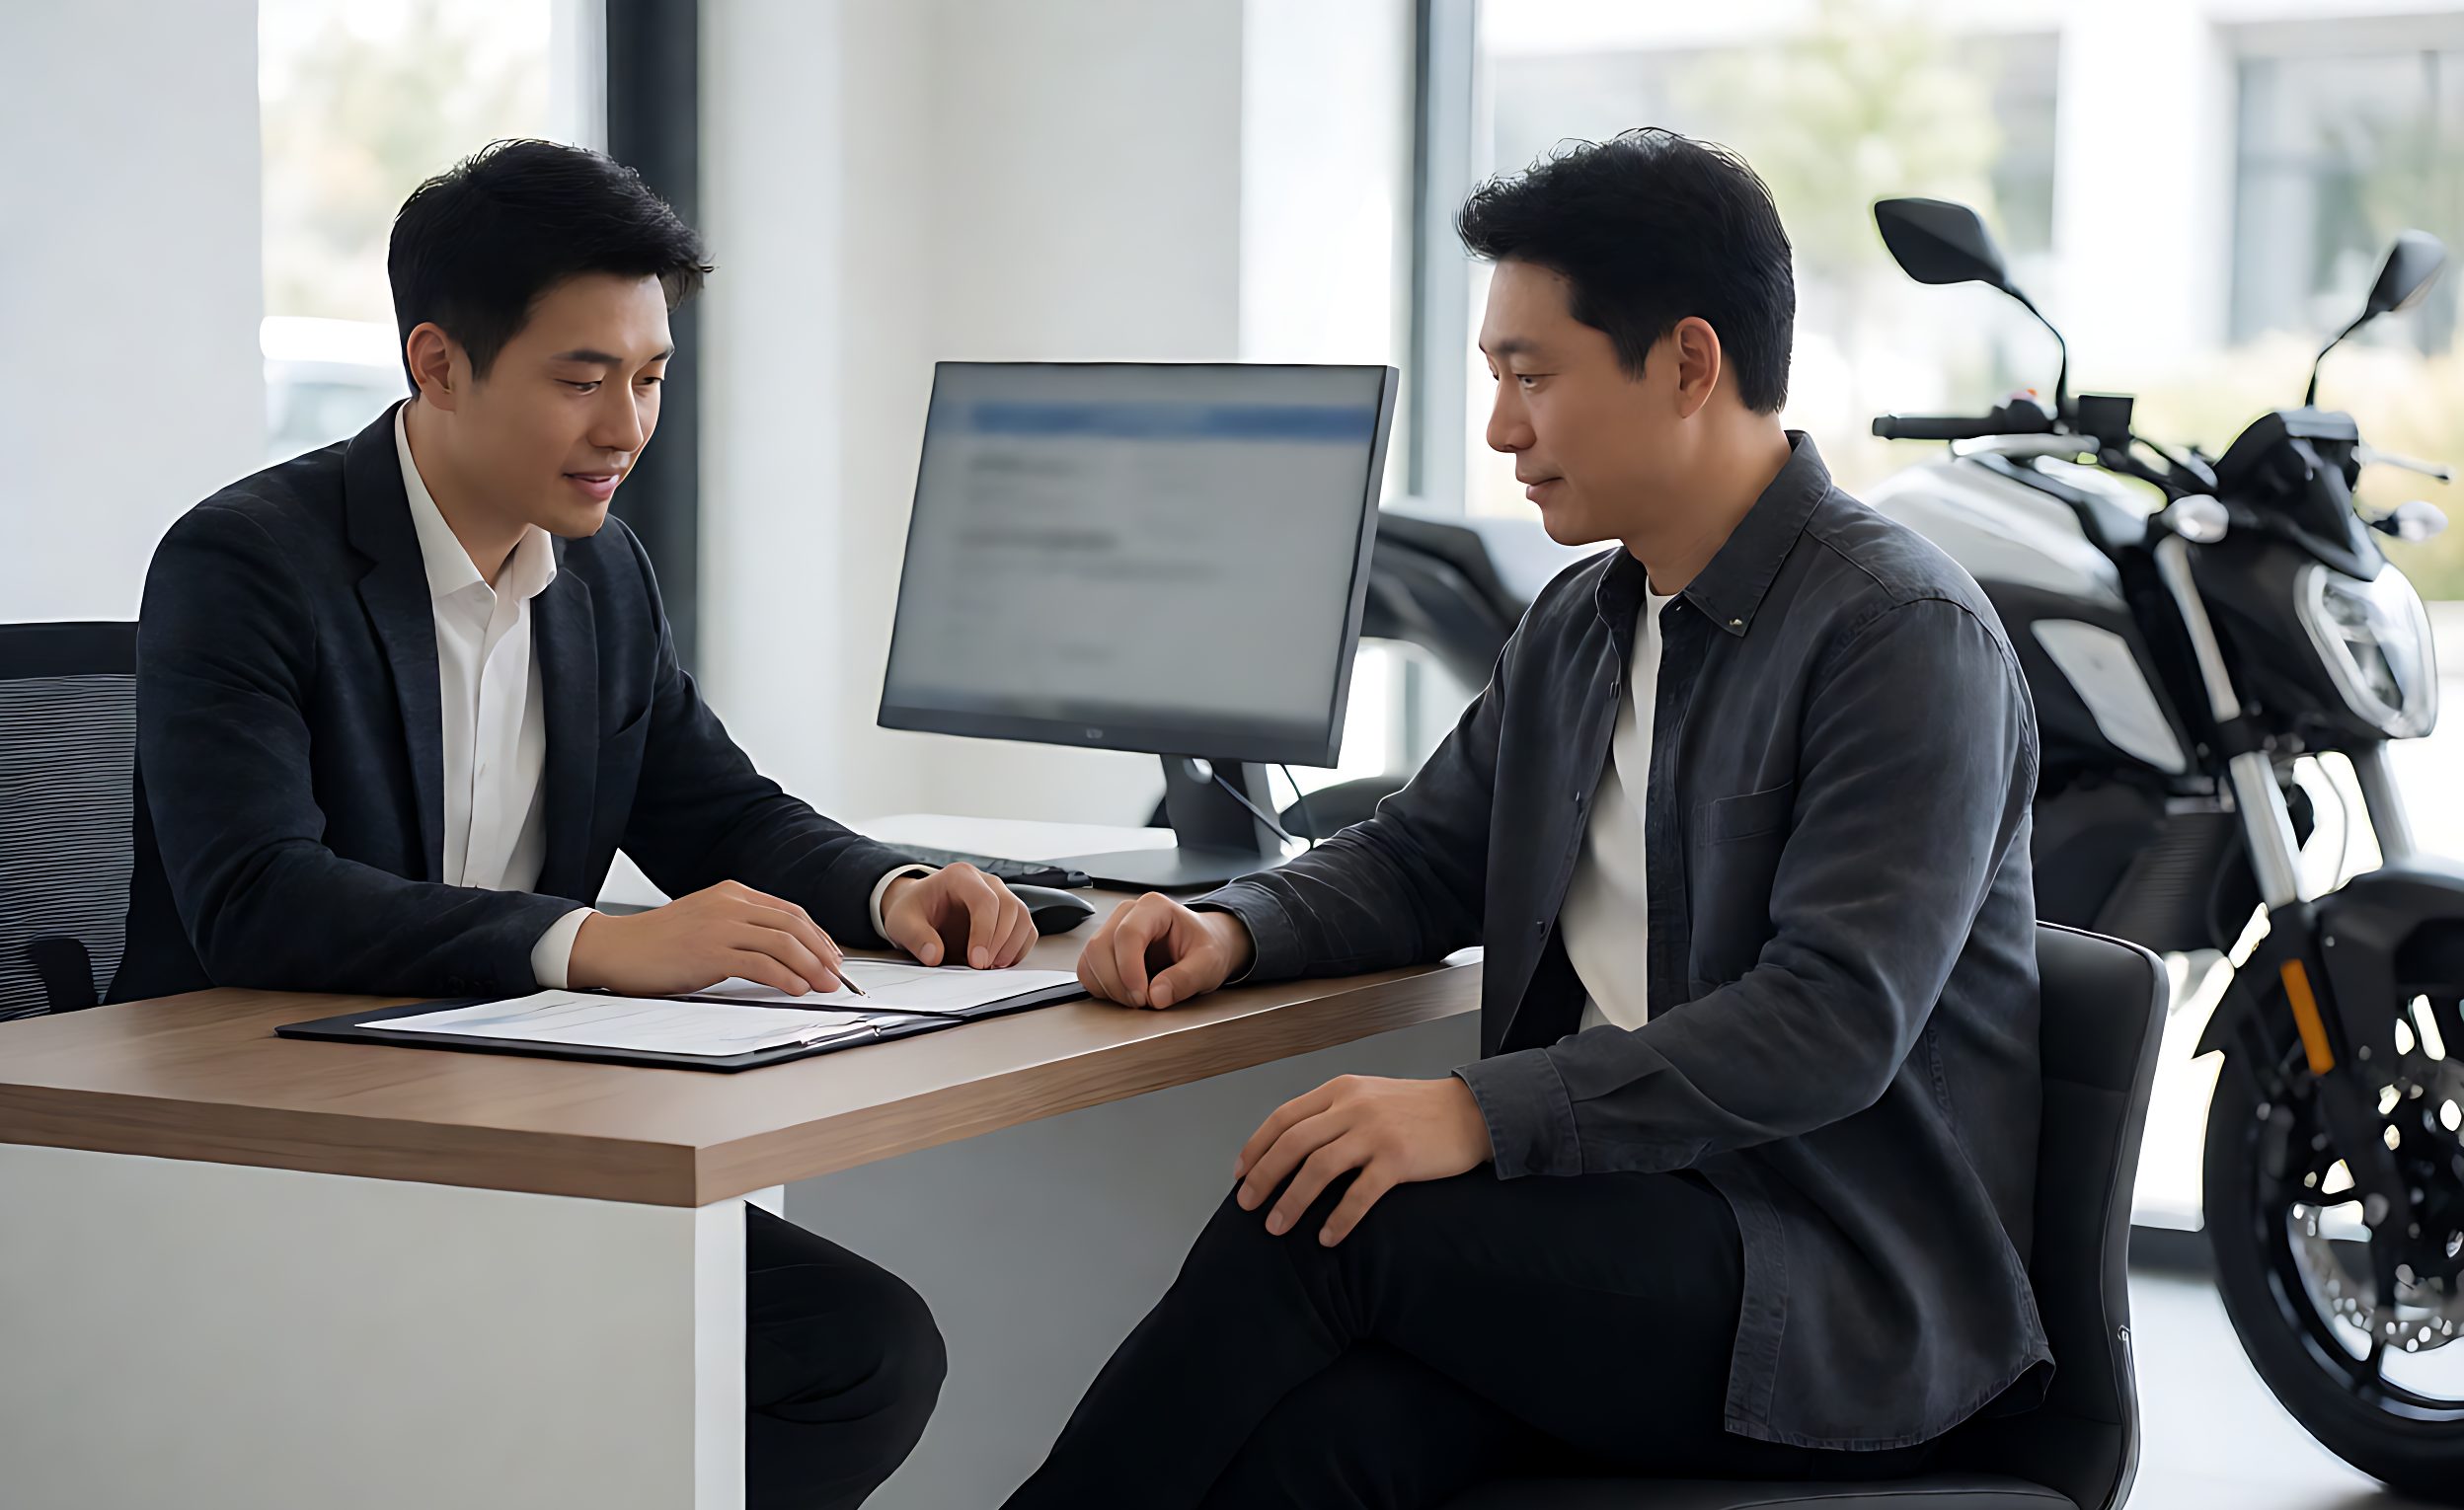
Almost every motorcycle a dealership sells must be insured within days, and in most markets the owner has to arrange that alone, in a hurry, from a call centre that has never seen the bike. A dealership that can complete the insurance at the point of sale removes a chore from the customer, collects a commission and – the part most dealers underestimate – acquires the renewal book, an asset that produces income for years without a corresponding sales effort.
The economics are worth stating plainly. A dealership selling forty units a month that places cover on a third of them, at a modest commission per policy, earns a meaningful monthly sum from a process that takes twenty minutes per transaction. Add renewals and the figure compounds, because the renewal requires no acquisition cost at all. This is ordinary commission income on a product the customer was going to buy anyway.
What an Insurance Partnership Actually Is
Three structures exist, and the difference between them is regulatory rather than commercial. In some markets a dealership may only refer the customer and must not discuss cover, price or terms; in others the dealership may act as a licensed agent and bind cover; in a few, an appointed representative arrangement lets trained staff sell under the insurer’s licence. Choosing the wrong structure is the fastest way to lose the partnership and, in regulated markets, to attract a penalty.
- Referral: name, contact and vehicle details passed to the insurer, who sells direct. Lowest compliance burden, lowest revenue.
- Agent or appointed representative: trained staff quote and bind under licence. Higher revenue, real compliance obligations.
- Broker arrangement: the dealership works through a licensed broker who holds the regulatory responsibility and shares commission.
In all three cases the underlying product is ordinary vehicle insurance, and the dealership’s value to the insurer is the same: a customer standing in front of a vehicle they have just decided to buy, at the exact moment cover becomes relevant.
The Three Revenue Streams
Dealers who treat insurance as one-off commission leave most of the value on the table. The revenue has three parts, and only the first is visible on the day of the sale.
- New policy commission: a percentage of the first premium, paid after the policy is bound and the cooling-off period passes.
- Renewal income: a share of subsequent years’ premiums. This is the stream that turns insurance into an asset, and it requires that the dealership, not the insurer, owns the renewal relationship in the agreement.
- Claims referral and repair work: an accident repair steered back into the dealership’s workshop carries parts and labour margin that often exceeds the commission on the original policy.
The third stream depends on something the dealership controls: whether its workshop is on the insurer’s approved repairer list. Getting on that list is a commercial negotiation – labour rates, parts sourcing, turnaround commitments – and it is usually easier to win after the partnership has produced a year of clean volume.
Compliance: Licensing, Disclosure and Consent
Insurance is a regulated product, and the obligations sit with whoever sells it. Four items belong in the operating manual before the first policy is quoted.
- Licensing: the correct authorisation for the structure being used, with named individuals registered and their training records on file.
- Disclosure of commission: in many jurisdictions the customer must be told that the dealership is paid, and in some, how much. A scripted disclosure delivered before the quote is cheaper than a complaint.
- Data consent: passing a customer’s contact details to a third party requires consent, recorded, and the consent must cover renewal contact as well as the initial sale.
- No tied-selling: insurance must never be a condition of buying the motorcycle, discounting the bike or approving finance. Regulators treat that seriously and customers remember it.
Where a dealership also arranges finance, the two products should be presented separately with separate signatures, because bundling them is where complaints originate and where the dealer financing discipline meets conduct risk.
Choosing an Insurer to Partner With
The insurer’s brand affects the dealership’s, because a customer who has a bad claims experience blames the place they bought the policy. Evaluate on four axes rather than on commission rate alone.
- Claims service: average settlement time and the proportion of claims settled without dispute – the only numbers that matter to the customer.
- Coverage fit: does the product cover the actual use case, including commercial delivery use, which standard personal policies frequently exclude?
- Underwriting appetite: the displacement bands and rider age brackets the insurer will actually quote, since a partner that declines half the showroom is not a partner.
- Systems: can a quote be produced in under ten minutes at the desk? If not, the process will be abandoned on busy Saturdays.
Exclusivity is the main negotiating lever, and it cuts both ways. An exclusive arrangement buys a higher rate and marketing support; a non-exclusive arrangement lets the desk place the customer with whichever insurer will actually quote them. Most dealerships are better off with one primary partner and one fallback, and the principle is the same one that governs territory and agreement terms: exclusivity should be paid for, not granted.
Selling Insurance Without Losing the Bike Sale
The failure mode of an insurance desk is a customer who came for a motorcycle and left feeling processed. Three practices keep the transaction clean: raise cover at the point where it is genuinely useful – after the bike is chosen, not before; present it as optional and say so out loud; and keep the handover simple, with the policy, the disclosure and the contact for claims in one envelope alongside the keys.
The moment is also an attachment opportunity that feels like service rather than upselling. A customer arranging cover is already thinking about theft and damage, which is exactly when the accessory and security bundles sell themselves, and when a training session is easiest to book – the rider training program reduces both the risk the insurer is pricing and the customer’s own anxiety.
Running the Desk: Process and Metrics
Insurance revenue is a process business, and the process is short enough to write on one page: offer at handover, quote within ten minutes, disclose the commission, record consent, bind, file the policy against the vehicle record, and set the renewal contact date. The filing step matters more than it looks, because a policy filed against the frame number is what makes the renewal book manageable and what links claims back to the vehicle’s service history.
- Placement rate: policies placed as a share of units delivered. Below a fifth usually means the offer is being skipped, not declined.
- Commission per unit delivered: the number that belongs in the monthly gross calculation.
- Renewal retention: the share of policies renewing through the dealership, and the single best indicator of whether the book is an asset.
- Claim repair capture: the share of customer accidents repaired in-house, which converts the insurance relationship into workshop margin.
One caution closes the loop. Insurance income depends on a customer relationship that takes years to build and one bad claims experience to lose, so the dealership should push the insurer harder on claims service than on commission rate. A partner who pays less and settles fast is worth more than one who pays more and argues, and the dealership is the party the customer will call either way. Warranty and goodwill handling follow the same logic, which is why the garantía discipline and the insurance desk should share one standard for how a customer is treated when something goes wrong.
One structural point decides whether the desk makes money: who owns the renewal. A partnership where the insurer retains the customer and pays only for the introduction produces a small one-off fee, while an arrangement where the dealership holds the renewal contact and the service relationship produces recurring income recurring revenue that survives staff turnover and model changes.
Preguntas Frecuentes
What are the three partnership structures?
Referral, where the insurer sells direct; agent or appointed representative, where staff bind cover; and broker arrangements where a licensed broker holds the duty.
Where does the revenue come from?
New policy commission, renewal income on subsequent years, and repair work captured when a claim comes back to the workshop.
What compliance items are essential?
Correct licensing, disclosure of commission, recorded data consent, and never making insurance a condition of the sale.
How should an insurer be chosen?
On claims service, coverage fit for the real use case, underwriting appetite and quote speed – not on commission rate alone.
Is exclusivity worth granting?
Only if it is paid for with a higher rate or marketing support. One primary partner plus a fallback is usually better.
How can insurance be sold without pressure?
Raise it after the motorcycle is chosen, state that it is optional, and hand over policy and claims contact with the keys.
Which metrics should the desk track?
Placement rate, commission per unit delivered, renewal retention and claim repair capture.